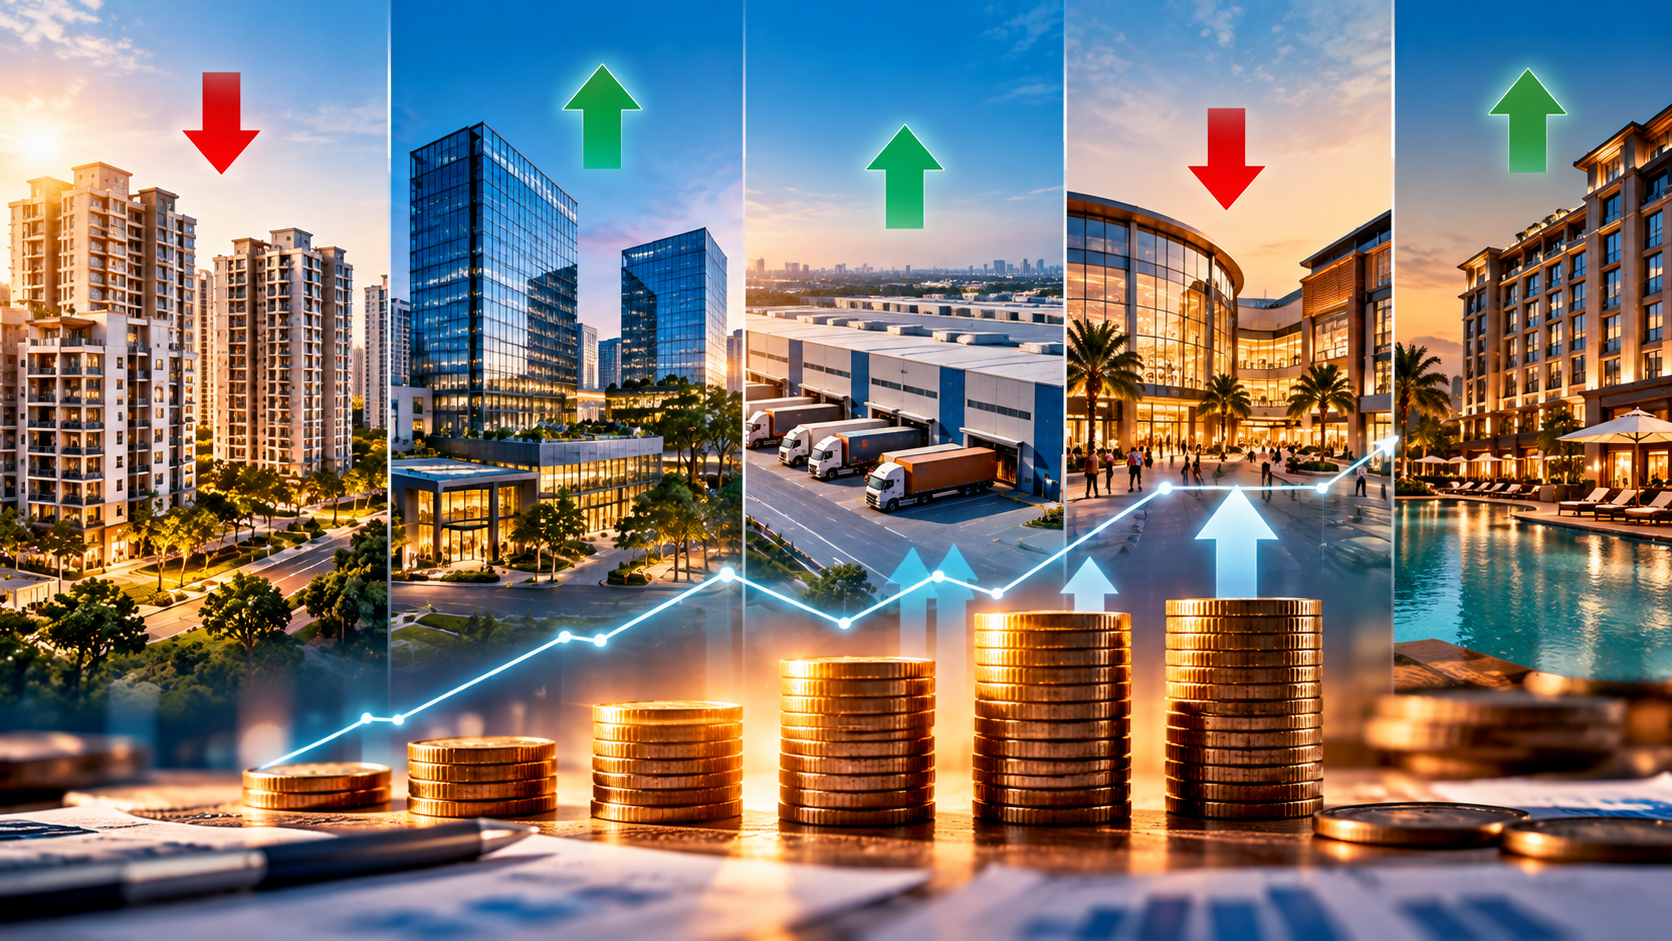
Office, mixed-use and industrial assets attract stronger capital flows, while residential and retail investments decline amid changing risk-return preferences
Institutional investment in India’s real estate sector is showing a clear shift in investor preferences, with capital increasingly moving towards operational office assets, mixed-use developments, industrial and logistics parks and hospitality projects. According to data from Colliers India, institutional investment in residential assets declined 39 per cent year-on-year to $694.5 million during January-September, compared with $1.14 billion in the corresponding period last year.
The decline comes as real estate developers increasingly rely on internal accruals and other funding sources to finance residential projects. At the same time, institutional investors appear to be favouring assets that provide greater visibility on cash flows and potentially more predictable returns.
Office Real Estate Emerges as the Preferred Investment Segment
Office assets remained the strongest institutional investment destination during the first nine months of the year. Investment in the segment increased 46 per cent to $2.17 billion, compared with $1.48 billion in the year-ago period.
The strong inflow reflects sustained demand for high-quality Grade A office properties, supported by leasing activity from global capability centres, technology companies, financial services firms and other large occupiers.
A key feature of the office market has been the growing participation of domestic investors. According to Colliers, domestic capital accounted for more than 90 per cent of institutional inflows into office assets during January-September.
The preference for operational assets is also significant because such properties can offer investors relatively visible rental income compared with development-stage projects.
Residential Investment Faces a Funding Shift
The 39 per cent decline in institutional investment in residential assets does not necessarily indicate weakness in housing demand.
Instead, the data points towards a change in the way developers are financing projects. Strong residential sales and cash flows have allowed several established developers to fund new projects through internal accruals, reducing their dependence on institutional capital.
Residential investments that did take place were largely directed towards development projects. This differs from the office segment, where investors showed a stronger preference for completed or operational assets.
The trend could continue if housing demand remains strong and developers maintain healthy cash generation from project sales.
Industrial and Logistics Assets Continue to Attract Capital
Industrial and logistics real estate also recorded healthy growth. Institutional investment in the segment increased 15 per cent to $371.9 million from $324.7 million in the corresponding period.
The expansion of organised manufacturing, e-commerce, third-party logistics and supply-chain infrastructure is supporting demand for modern warehouses and industrial facilities.
The government's focus on manufacturing and infrastructure development could provide an additional structural boost to the segment. Rising formalisation of logistics and the increasing need for strategically located distribution centres are also improving the long-term investment case.
Mixed-Use Projects See Strong Growth
Mixed-use developments recorded a significant increase in institutional investment. Capital flows into the segment rose 42 per cent to around $1.01 billion during January-September, compared with $707.8 million a year earlier.
Mixed-use projects can provide investors with exposure to multiple real estate categories, including residential, commercial, retail and hospitality. Their diversified revenue potential can become particularly attractive when investor preferences are shifting across risk and return profiles.
The strong growth in this category indicates that investors are increasingly looking beyond conventional standalone real estate assets.
Retail Real Estate Records Sharp Decline
Retail real estate was among the weakest segments during the period. Institutional investment in shopping malls declined 78 per cent to $85.2 million from $380 million in the year-ago period.
The sharp decline highlights the uneven flow of institutional capital across real estate categories. Although consumer spending and organised retail activity remain important drivers for commercial property, investors appear to be more selective when allocating capital to retail assets.
The availability of high-quality assets, rental yields, location and tenant mix are likely to remain important considerations for future investment decisions.
Hospitality Investment Surges
Hospitality emerged as another major bright spot, with institutional investment jumping sharply to $632.2 million from just $88.2 million in the corresponding period last year.
The surge reflects increasing investor confidence in India's travel, tourism and business-hospitality demand. Rising domestic travel, improving business activity and stronger demand for premium accommodation could continue to support investment in hotels and related assets.
The significant increase also demonstrates the broadening of institutional interest beyond traditional residential and office real estate.
Domestic Capital Becomes Increasingly Important
One of the most important trends highlighted by the data is the increasing role of domestic capital in India's real estate market.
Alternative Investment Funds, family offices, private equity investors, pension funds, banks, real estate platforms, listed REITs, sovereign wealth funds and other institutional investors are contributing to the growing depth of India's property investment ecosystem.
Domestic investors have become particularly important in the office segment, where they contributed more than 90 per cent of institutional inflows during the first nine months.
A deeper domestic capital pool could help reduce the sector's dependence on overseas funding cycles and global liquidity conditions.
Foreign Investment Could Provide the Next Catalyst
While domestic capital is playing a larger role, the outlook for foreign investment remains important. Changes in global interest rates, currency movements and international risk appetite could influence foreign capital flows into Indian real estate.
According to Colliers, evolving investor preferences across the risk-return spectrum, combined with increasing domestic capital depth, are expected to support real estate investment in India. An improvement in foreign investment volumes could provide another boost in the coming quarters.
What It Means for the Real Estate Sector
The investment data suggests that India's real estate market is becoming increasingly differentiated. Strong investment in offices, mixed-use developments, industrial and logistics assets and hospitality contrasts sharply with the decline in residential and retail institutional funding.
For developers, access to capital is likely to depend increasingly on the quality of assets, location, execution capabilities and visibility of future cash flows.
For investors, operational assets with stable rental income may continue to command a premium, while development projects could attract capital where the potential returns adequately compensate for execution and market risks.
Market Outlook
India's real estate investment cycle remains structurally positive, but capital allocation is becoming more selective. Office assets are currently benefiting from strong leasing momentum and domestic institutional participation, while industrial, logistics, mixed-use and hospitality properties are emerging as additional areas of interest.
The sharp decline in institutional residential investment should not be interpreted in isolation, as developers' growing ability to fund projects through internal accruals is an important factor. Similarly, the decline in retail investment reflects capital selectivity rather than necessarily a broad deterioration in consumer or retail activity.
Going forward, interest rates, domestic liquidity, foreign capital flows, office leasing, residential sales, infrastructure spending and the performance of commercial assets will remain key indicators for the sector.
The broader picture remains encouraging: India's expanding economy, urbanisation, infrastructure development and formalisation of real estate markets could continue to attract institutional capital. However, investors are likely to remain focused on assets offering stronger visibility of cash flows, sustainable yields and attractive risk-adjusted returns.